Do you employ staff with HECS Debts …………Beware of their traps!
We have had a number of employed professionals stung by the HECS repayment trap recently!
These are the traps to lookout for …
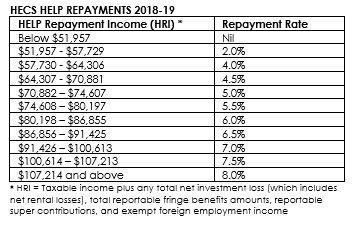
A professional earning under $51,957 has NO HECS to pay… now that is a package of $56,892 including Super.
Once their Gross earnings goes to $51,958, their entire earnings is subject to 2% HECS.
Here is a real life case study:
- Person on package of $56K, Ex super = $51,142 per annum
- Receives a Christmas bonus of $1,000
- Tax on bonus will be 34.5% or $345 (32.5 % plus Medicare)
- New Gross income is $51,142 + $1,000 = $52,142
- HECS on total income will go from NIL to $1,043 ($52,142 * 2%)
- The tax man will put his hand out for $1,388 ($345 + $1,043) on the Christmas bonus.
Yes the $1,043 does come off the HECS debt, BUT it doesn’t feel good when it comes as a year-end tax bill!
If the employee was to earn $6,600 then the HECS gets bigger again as the repayment rate moves to 4%.
If the employee was to earn $6,600 then the HECS gets bigger again as the repayment rate moves to 4%.
The moral of the story is, if you have people on incentives, you need to be very careful to show them how the bonus can move them through the HECS repayment levels.
If their base pay stays below the threshold and extra is NOT deducted through the year to compensate for the effect of the bonus, they will end up with a big tax bill, generated by HECS.
originally published in December 2018 Cascade Newsletter